

Real yields take the lead
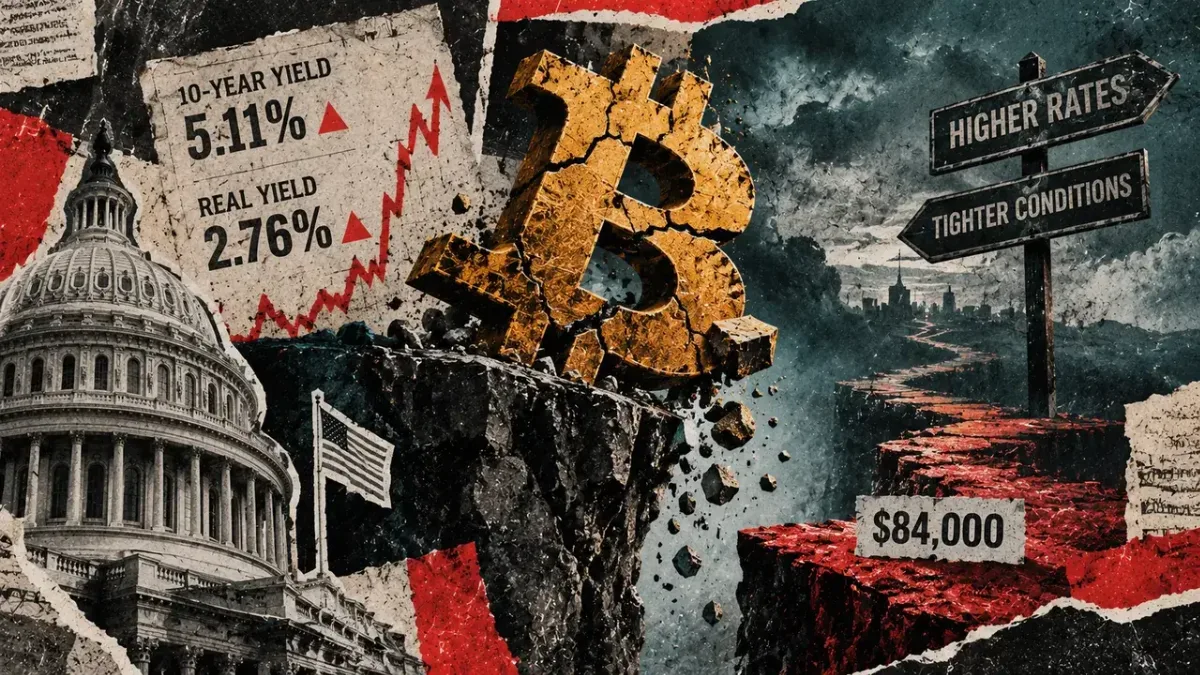
The US 10-year Treasury yield closed at 5.11% on Sept. 23 after gaining 15 basis points, intensifying pressure on Bitcoin. S&P Global’s composite PMI rose to 58.4 from 56.0, with services at 58.7 and manufacturing at 57.0, the strongest expansion since July 2021. The report reduced expectations for rapid Federal Reserve easing after the central bank raised its target range to 3.75%-4.00% on Sept. 16.
The 10-year real yield, which removes expected inflation, jumped from 2.63% to 2.76%, absorbing 13 of the 15 basis-point rise. Inflation compensation edged from 2.33% to 2.35%. That shift raised the inflation-adjusted return on government debt and the opportunity cost of holding Bitcoin, which provides no yield.
Bitcoin fell to an intraday low of $83,500 and saw roughly $280 million in long liquidations as it broke below $84,000, according to CoinGlass. The 10-year traded near 5.058% shortly after the PMI release before settling at 5.11%.
On-chain support comes into focus
Glassnode places the largest cluster of long-term holder supply between $84,000 and $85,000, making the area the nearest on-chain support and a key daily-close battleground. From a quote near $84,282, the True Market Mean at $77,000 is about 8.6% lower. Bitcoin remains above both that mean and short-term holders’ cost basis.
A single wick below $84,000 leaves Glassnode’s structure intact, but sustained daily closes below the zone would expose $77,000. The first major upside reference is $96,700, derived from mean MVRV, roughly 14.7% above the current quote.
ETF demand offers support
ETF demand has cushioned the selloff. Spot Bitcoin ETFs received about $1.3 billion over five days, ending two weeks of outflows. Farside Investors recorded $999 million on Sept. 21, $714.7 million on Sept. 22 and $346.9 million on Sept. 23. IBIT led Sept. 22 with $350.3 million, followed by FBTC at $257.4 million and MSBT at $99 million.
Exchange spot volume rose 121% from its August trough over the same period. Glassnode’s on-chain and ETF observations run through Sept. 21, while its spot-volume data runs through Sept. 22; Farside’s Sept. 23 figures show inflows continued during the bond selloff, though more slowly.
Two paths from $84,000
Friday adds roughly $16 billion in Bitcoin options expirations on Deribit, US durable goods and consumer sentiment data, and CME’s September Bitcoin futures settlement. A recovery path requires the real yield to fall below about 2.65%, positive ETF flows, expanding up-day volume and daily closes inside $84,000-$85,000. If real yields reach 2.85%-2.90%, flows weaken and BTC loses support, $77,000 becomes the active reference.
Market context
Market data reflects conditions at publication time and is not updated in real time.
Data captured at: Sep 25, 2026 06:48 (Tehran)
Likely market impact
| Segment | Outlook |
|---|---|
| Bitcoin | ▼ Bearish |
| Ethereum | ● Neutral |
| Altcoins | ● Neutral |
| Short term | ▼ Bearish |
| Long term | ● Neutral |
Spot prices at publication
Fear & Greed Index
Chart
Source: CryptoSlate